-
Resources
-
Pricing
This timeline traces the development of insurance from ancient systems of shared risk to the complex global industry of today. More Less
Build a timeline like this one in minutes, for free. Start Yours →
1000 BCE - 800 BCE
The general average principle associated with the Lex Rhodia is often traced to the Greek island of Rhodes between approximately 1000 and 800 BCE. It required participants in a maritime venture to share losses incurred to save the common voyage.
Image source: General average
400 BCE
In the fourth century BCE, loan rates varied according to whether a voyage occurred during safer or more dangerous times of year. This variation implied an early form of risk pricing with an effect similar to insurance.
300 BCE
Concepts resembling insurance have been identified in third-century BCE Hindu writings, including the Dharmasastra, Arthashastra, and Manusmriti.
133
A burial society collegium established at Lanuvium around 133 AD collected membership dues and prescribed rules for mutual assistance. Its regulations were preserved on a later tablet discovered in Egypt.
220
The Roman jurist Ulpian compiled a life table around 220 CE during the reign of Elagabalus. The table was later incorporated into Justinian's Digesta and became an important historical reference for life expectancy and actuarial calculation.
Image source: Ulpian
235
Roman jurist Paulus wrote a legal opinion on the Lex Rhodia around 235 CE. Preserved in Justinian's Digesta, it articulated the general average principle for maritime losses.
Image source: General average
533
The Digesta seu Pandectae, completed under Justinian I in 533, preserved Roman legal material concerning maritime risk and life tables. These texts later supplied historical evidence for the development of insurance law and actuarial science.
Image source: Digest (Roman law)
1816
An archaeological excavation at Minya, Egypt, produced a Nerva–Antonine-era tablet from Antinoöpolis. The tablet prescribed the rules and dues of the Lanuvium burial society.
Image source: Antinoöpolis
1851
Joseph P. Bradley, later a U.S. Supreme Court justice and formerly an actuary, published a historical account of Ulpian's Roman life table in the Journal of the Institute of Actuaries.
Image source: Joseph P. Bradley
Dec 1901 - Jan 1902
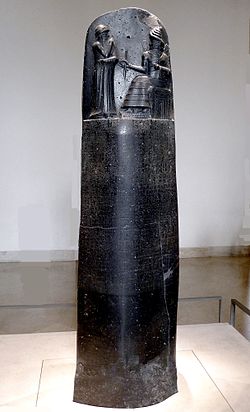
At the direction of archaeologist Jacques de Morgan, Father Jean-Vincent Scheil discovered the Code of Hammurabi stele at Shush in December 1901 and January 1902. The monument contains thousands of lines of cuneiform law, including provisions associated with commercial risk.
Image source: Code of Hammurabi
1236
Pope Gregory IX condemned foenus nauticum, or maritime lending, as usury in his 1236 decretal Naviganti. Commenda contracts were introduced in response to restrictions on maritime finance.
Image source: Pope Gregory IX
1250 - 1350
During the thirteenth and early fourteenth centuries, European traders traveled widely and sought protection against theft, fraud, and misconduct by captains or crews, risks sometimes identified as Risicum Gentium.
1275 - 1299
By the late thirteenth century, Italian merchants increasingly separated risk management from finance. Cambium contracts financed trade through discounted bills of exchange rather than through arrangements directly tied to a sea voyage.
1293
Denis of Portugal established the Bolsa de Comércio by mutual agreement on 10 May 1293. It is regarded as the first documented form of marine insurance in Europe.
1310
The Chamber of Assurance was established in 1310 in Bruges, a major Flemish commercial city. Its creation reflected the growing need for organized mechanisms to manage commercial and maritime risks.
Image source: Bruges
Feb 13, 1343
Professor Federigo identified written insurance contracts dating to 13 February 1343 in Pisa. These documents predate the traditionally cited first Italian marine insurance contract of 23 October 1347.
1347
The first known insurance contract is traditionally dated to Genoa in 1347. During the following century, maritime insurance spread widely and premiums were increasingly varied according to perceived risks.
1347 - 1399
In fourteenth-century Genoa, separate insurance contracts were developed independently of loans and other financial agreements. Insurance pools backed by pledges of landed estates also emerged.
1369
Genoa introduced insurance regulation and fines in 1369 for violations of church prohibitions against usury involving sea loans and commenda contracts. Specialized courts also developed to resolve maritime insurance disputes.
Image source: History of insurance
1400 - 1499
During the fifteenth century, the word policy became standardized as a term for an insurance contract, helping establish a consistent vocabulary for the developing industry.
Image source: Insurance policy
1435
A Barcelona ordinance issued in 1435 required traders to use formal courts when resolving insurance disputes. It marked a move away from reliance on informal arbitration.
Image source: Barcelona
1436
Venice established the Consoli dei Mercanti in 1436 as a specialized court for maritime insurance matters. The court reflected the growing institutionalization of commercial insurance law.
Image source: Venice
1488 - 1552
Pedro de Santarém wrote On Insurance and Merchants' Bets in 1488. Published in 1552, it is regarded as the first printed book devoted to insurance.
Image source: Santarém, Portugal
1520
In 1520, Genoa replaced its mercantile court with the more specialized Rota. The court followed merchants' customs while also incorporating formal legal rules.
Image source: Roman Rota
1500 - 1599
During the sixteenth century, traders increasingly turned to formal courts because informal arbitrators lacked the power to enforce their decisions. This strengthened the legal infrastructure of insurance.
Image source: Insurance law
1500 - 1599
By the sixteenth century, insurance had become common among merchants in Britain, France, and the Netherlands. Maritime commerce was a major driver of this expansion.
1600 - 1699
In the seventeenth century, merchants began arranging insurance outside their home countries. Reduced trade or higher local insurance costs encouraged the use of international markets.
1600 - 1629
Some forms of insurance developed in London during the early decades of the seventeenth century, as the city grew into an important center of commerce and maritime finance.
1600 - 1699
Before modern-style insurance became established in the late seventeenth century, friendly societies operated in England. Members contributed to a common fund that could provide assistance during emergencies.
Image source: Friendly society
1666
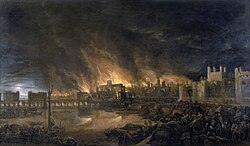
The Great Fire of London destroyed more than 13,000 houses in 1666. Its devastating effects transformed property insurance from a matter of convenience into an urgent need.
Image source: Great Fire of London
1667
In the plan for rebuilding London after the Great Fire, Sir Christopher Wren included a site for an insurance office in 1667, reflecting the growing public importance of property protection.
1676
Hamburger Feuerkasse was established in 1676 and became the first officially established fire insurance company in the world. It is also the oldest existing insurance enterprise available to the public.
Image source: Great fire of Hamburg
1681
Economist Nicholas Barbon and eleven associates founded the Insurance Office for Houses in 1681. Located behind the Royal Exchange, it insured brick and frame homes against fire.
Image source: Nicholas Barbon
1693
Edmond Halley wrote the first life table in 1693. Although the table was an important foundation, the mathematical and statistical tools needed for modern life insurance developed only in the 1750s.
Image source: Edmond Halley
1696
The Hand in Hand Fire & Life Insurance Society was founded in 1696 at Tom's Coffee House in St Martin's Lane, London. It became a notable early fire and life insurance company.
Image source: Hand in Hand Fire and Life Insurance Society
1700 - 1799
The first life insurance policies were taken out in the early eighteenth century. The field later developed through improved mortality data, mathematics, and actuarial methods.
Image source: Life insurance
1700 - 1799
During the eighteenth century, Lloyd's Coffeehouse became a prominent marine insurance marketplace in London. European and American traders used it to insure shipments.
1706
William Talbot and Sir Thomas Allen founded the Amicable Society for a Perpetual Assurance Office in London in 1706. It is regarded as the first company to offer life insurance.
Image source: Amicable Society for a Perpetual Assurance Office
1710
The Sun Fire Office dates from 1710 and is the earliest still-existing property insurance company.
Image source: Sun Alliance (company)
1720
The Royal Exchange Assurance Corporation received its royal charter in 1720 under the Royal Exchange and London Assurance Corporation Act 1719.
Image source: Royal Exchange Assurance Corporation
1732
The first insurance company in colonial America to underwrite fire insurance was formed in Charles Town, modern-day Charleston, South Carolina, in 1732.
1752
In 1752, Benjamin Franklin founded the Philadelphia Contributionship for the Insurance of Houses from Loss by Fire, an important early American property insurer.
Image source: Philadelphia Contributionship
1759
The Presbyterian Synods in Philadelphia and New York founded the Corporation for Relief of Poor and Distressed Widows and Children of Presbyterian Ministers in 1759.
Image source: Presbyterianism in the United States
1762
Edward Rowe Mores established the Society for Equitable Assurances on Lives and Survivorship in 1762 after earlier efforts by his disciple to obtain a charter had failed.
Image source: The Equitable Life Assurance Society
1769
Episcopalian priests created a relief fund in 1769 comparable to the Presbyterian fund established a decade earlier, extending organized mutual assistance to another religious community.
1774
In 1774, participating members of the insurance arrangement associated with Lloyd's moved to the Royal Exchange on Cornhill and formed the Society of Lloyd's. Lloyd's operated as a gathering place for underwriters rather than as an insurance company.
Image source: Lloyd's of London
1775 - 1830
William Morgan was appointed in 1775 and served until 1830. He is regarded as the first modern actuary because of his systematic application of mathematical methods to life insurance.
Image source: William Morgan (actuary)
1776
In 1776, the Society for Equitable Assurances carried out the first actuarial valuation of liabilities. It later distributed the first reversionary bonus in 1781 and an interim bonus in 1809.
1800 - 1899
In the late nineteenth century, accident insurance became increasingly available. The new coverage reflected industrialization, urbanization, and the hazards of rail travel and modern employment.
1848
The Railway Passengers Assurance Company was formed in England in 1848 and became the first company to offer accident insurance. It responded to rising fatalities on the expanding railway system.
Image source: Aviva
1870 - 1899
By the late nineteenth century, governments began initiating national insurance programs against sickness and old age, marking a transition from private mutual protection toward public social insurance.
Image source: Social insurance
1911
The British National Insurance Act 1911 gave working-class people the first contributory system of insurance against illness and unemployment.
Image source: National Insurance Act 1911
1913
By 1913, approximately 2.3 million people were insured under the British unemployment benefit scheme and nearly 15 million were insured for sickness benefits.
May 19, 1924
The United States passed the World War Adjusted Compensation Act, or Bonus Act, on 19 May 1924. It granted World War I veterans a life insurance policy and later contributed to the Bonus Army movement of 1932.
Image source: World War Adjusted Compensation Act
1935
The New Deal's Social Security Act of 1935 expanded the concept and acceptance of insurance as a means of providing financial security for older workers. Before 1935, the federal government had not mandated nationwide insurance.
Image source: Social Security Act
1944
The original G.I. Bill of 1944 created large-scale programs that expanded the idea that educational expenses and affordable housing mortgages could be benefits of military service.
Build a timeline like this one in minutes, for free. Start Yours →
Or browse the full history timeline directory, with more than 2,500 topics.
This History of Insurance timeline was generated with the help of AI, using information found on the internet.
We work hard to keep these timelines accurate, but mistakes do get through. If you spot one, email us at [email protected] and we'll fix it for future visitors.
Generate yours with AI or build it from scratch, for free.
Export your timeline, add your own events, edit or remove AI-generated events, and much more
No credit card required.
15-day money-back guarantee.
You can create an unlimited number of timelines with up to 10 events on each one, customize how they look, export them to PDF, PNG, PowerPoint, CSV, and Excel, and share them with a link. Timelines made with Timeline Maker AI keep every event the generator created, and you can add up to 5 events of your own. Paid plans remove the event limit, add spreadsheet imports and hide Preceden's branding, and the higher-priced plan also adds collaborators, a custom logo and a custom domain.
Yes. You can cancel your subscription from your account page at any time, and you will not be charged again. Your subscription stays active for the rest of the period you already paid for.
Yes. We email you a reminder 15 days before your annual renewal, and we email you a receipt after every payment.
Yes. You can email us within 15 days of any payment, and we will issue you a full refund.
Check out our pricing docs or send us an email anytime: [email protected].